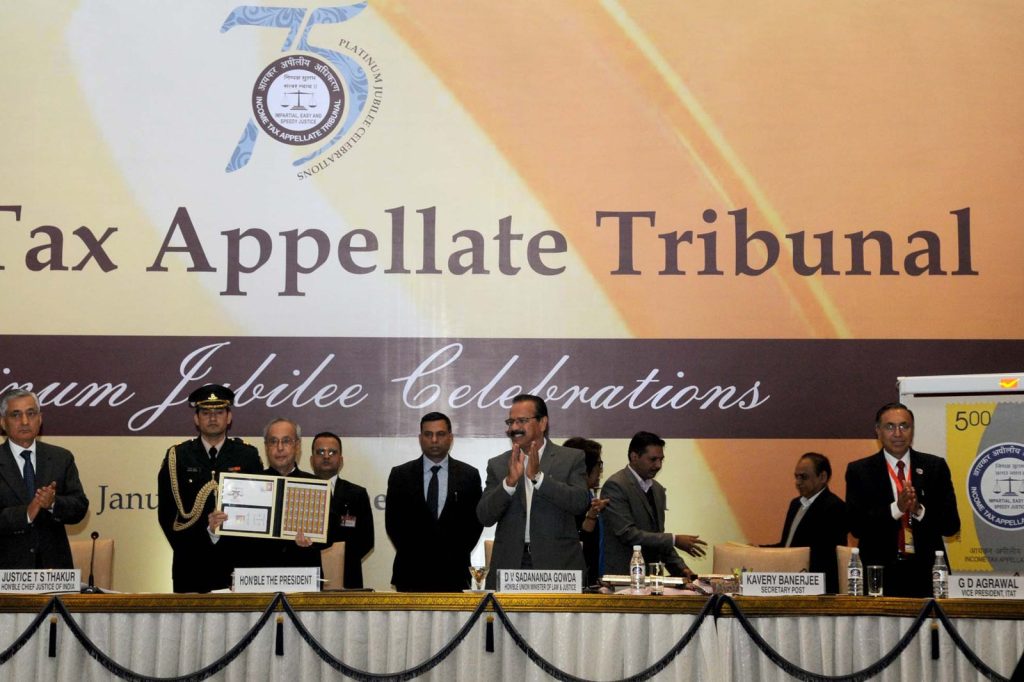
MUMBAI, June 28 — The Income Tax Department cannot simply add undisclosed income to a taxpayer’s return based on documents seized from a third party, the Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has ruled. Unless the department independently establishes that a buyer actually paid unaccounted cash, additions resting solely on a developer’s loose papers are unsustainable, the tribunal said. The case centred on Sanjeet Kumar Kedarnath Gupta, who jointly purchased a commercial unit in GNP Galaxy Phase I with his brother.
The property was registered via an agreement dated August 6, 2020, for ₹50 lakh. The trouble began after the tax department conducted a search on the GNP Group and its associated entities on September 23, 2021.
During that search, officials recovered loose papers and electronic records that allegedly contained details of payments received from buyers. On that basis, the department claimed Gupta had paid ₹90 lakh in cash as “on-money” for the property. It reopened his assessment for AY2019-20.
Gupta denied any cash payment. The entire consideration, he said, was paid through banking channels.
He also argued that the documents the department relied upon belonged to the developer and could not, by themselves, be treated as evidence against him. The ITAT agreed. It found that the tax department had failed to produce any independent evidence linking Gupta to the alleged cash payment.
Loose papers and electronic records from the developer, without corroboration, were insufficient to justify the addition under the Income-tax Act. The tribunal accordingly deleted the ₹90 lakh addition. The salient point, for all the noise about search-and-seizure operations, is that the burden of proof remains on the department.
It cannot outsource its case to a developer’s bookkeeping, however suspicious that bookkeeping might appear. The ruling reinforces a longstanding principle: third-party documents, without independent verification, do not make a taxpayer liable.
What to watch next is whether the department appeals to a higher forum, or whether this decision prompts a broader re-examination of how it treats “on-money” allegations in property transactions. For now, the tribunal has drawn a clear line.