Investors in Peabody Energy Corporation now face a hard choice. They can sit tight or step forward as lead plaintiffs in a securities fraud lawsuit. The Schall Law Firm, a Los Angeles-based shareholder litigation shop, put out the call on July 3, 2026.
The deadline to act is set by the court. No one has said exactly when that deadline falls.
The case itself is still young. No judge has ruled on whether the claims have merit. But the allegations are serious: Peabody Energy, the firm says, made false and misleading statements to the market.
Investors who bought BTU shares during a specific window may have been burned. The Schall Law Firm wants to hear from them.
This kind of lawsuit is not new. Securities fraud class actions follow a familiar rhythm. A law firm announces an investigation.
Investors are urged to contact the firm. A lead plaintiff is chosen. Discovery begins.
Sometimes the case settles. Sometimes it goes to trial.
Often it drags on for years. What makes this one different is the company at the center. Peabody Energy is not a small player.
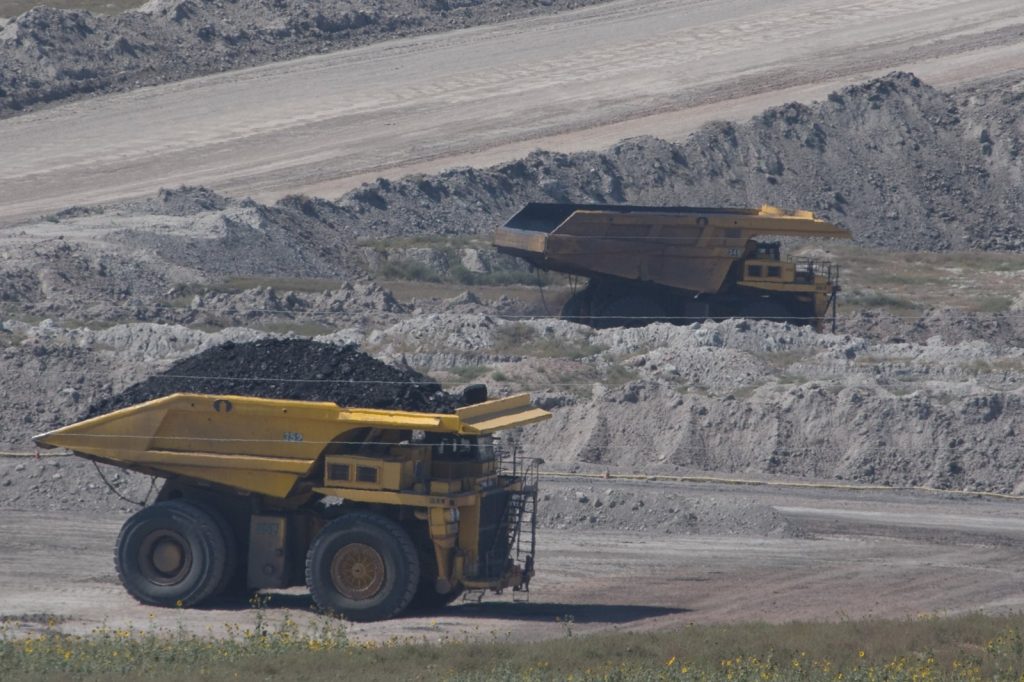
It is one of the largest coal companies in the world. Its stock trades on the New York Stock Exchange under the ticker BTU.
The company has been through turbulence before. It filed for bankruptcy in 2016 and emerged a year later. Now it faces allegations that it misled shareholders about its financial health or business practices.
The Schall Law Firm notice did not specify the exact nature of the alleged false statements. But the implication is clear: investors bought shares based on information that may have been wrong. For shareholders, the stakes are straightforward.
If the lawsuit succeeds, they could recover some of their losses. If it fails, they get nothing.
The Schall Law Firm is offering its services to those who believe they were misled. The firm specializes in this kind of work. Its notice encourages investors to contact the firm before the lead plaintiff deadline.
That deadline is the key date. Anyone who misses it cannot serve as the lead plaintiff.
They can still be part of the class, but they lose the right to direct the litigation. Why does this matter now? Coal companies have been under pressure for years.
Environmental regulations, competition from natural gas, and the shift toward renewable energy have squeezed the industry. Peabody has tried to adapt. It has cut costs, sold assets, and focused on its most profitable mines.
But the company still faces headwinds. A lawsuit like this adds another layer of risk.
It forces management to spend time and money on legal defense. It can distract from running the business. And if the allegations prove true, the damage to Peabody’s reputation could be lasting.
The Schall Law Firm is clear about what it wants. It wants investors who suffered losses to step forward.
It wants a lead plaintiff who can represent the class. And it wants the court to certify the case as a class action. That is the standard path.
The firm has done this before. It has filed similar lawsuits against other companies. Its track record is not part of the public notice.
For now, the ball is in the investors’ court. They have to decide whether to join the case.
They have to weigh the potential recovery against the time and effort involved. They have to watch the calendar. The deadline will come.
After that, the case will move forward with or without them.